
Monday, November 16, 2009
At Least One Central Bank Held Fake Gold
Rob Kirby seems like a fairly respectable fellow. But I am thoroughly agnostic about Kirby's claim that a large portion of the world's gold has been cut with tungsten. Big claims require big evidence, and I haven't seen it yet.
True, as Mike Hewitt points out, a Chinese company boasts about making gold-plated tungsten:
A coin with a tungsten center and gold all around it could not be detected as counterfeit by density measurement alone ... We are well accustomed to exploit more innovative applications of tungsten products. Gold-plated tungsten is one of our main products.But there is no evidence that gold-plated tungsten has been used as a counterfeit.
However, we do know that at least some gold held by central banks is fake. For example, as the BBC noted last year, some 90kg of gold held by Ethiopia's central bank was really gold-plated steel.
Obviously, this is not a first world country or banking center we're talking about. Ethiopia is one of the world's poorest countries.
But the fact that any central bank has fallen for fake gold means - in a rational world - that a full audit of the gold holdings of central banks worldwide should be conducted.


Chanos Shorts China
Famed short trader Jim Chanos thinks that China's economy has real problems and is overvalued. He's therefore shorting China.
As Politico writes.
Now, Chanos says he has found another “trust me” story: China. And he is moving to short the entire nation’s economy. Washington policymakers would do well to understand his argument, because if he’s right, the consequences will be felt here.
Chanos and the other bears point to several key pieces of evidence that China is heading for a crash.
First, they point to the enormous Chinese economic stimulus effort — with the government spending $900 billion to prop up a $4.3 trillion economy. “Yet China’s economy, for all the stimulus it has received in 11 months, is underperforming,” Gordon Chang, author of “The Coming Collapse of China,” wrote in Forbes at the end of October. “More important, it is unlikely that [third-quarter] expansion was anywhere near the claimed 8.9 percent.”
Chang argues that inconsistencies in Chinese official statistics — like the surging numbers for car sales but flat statistics for gasoline consumption — indicate that the Chinese are simply cooking their books. He speculates that Chinese state-run companies are buying fleets of cars and simply storing them in giant parking lots in order to generate apparent growth.
Another data point cited by the bears: overcapacity. For example, the Chinese already consume more cement than the rest of the world combined, at 1.4 billion tons per year. But they have dramatically ramped up their ability to produce even more in recent years, leading to an estimated spare capacity of about 340 million tons, which, according to a report prepared earlier this year by Pivot Capital Management, is more than the consumption in the U.S., India and Japan combined.
This, Chanos and others argue, is happening in sector after sector in the Chinese economy. And that means the Chinese are in danger of producing huge quantities of goods and products that they will be unable to sell.
The Pivot Capital report was extremely popular in Chanos’s office and concluded, “We believe the coming slowdown in China has the potential to be a similar watershed event for world markets as the reversal of the U.S. subprime and housing boom.”
And the bears also keep a close eye on anecdotal reports from the ground level in China, like a recent posting on a blog called The Peking Duck about shopping at Beijing’s “stunningly dysfunctional, catastrophic mall, called The Place.”
“I was shocked at what I saw,” the blogger wrote. “Fifty percent of the eateries in the basement were boarded up. The cheap food court, too, was gone, covered up with ugly blue boarding, making the basement especially grim and dreary. ... There is simply too much stuff, too many stores and no buyers.”
Can We Save America?
How come the Wall Street robber barons who brought on the financial crisis are still calling the shots and pillaging the economy?
Congress is bought and paid for, and the fox is guarding the chicken coop in the Executive Branch, with Summers and Geithner calling the shots.
The American people are furious at the giant banksters who have picked their pockets so they can make huge bonuses. But - so far - the American people have for the most part kept their volcanic anger to themselves.
Make A Little Noise
As MSNBC news correspondent Jonathan Capehart tells Dylan Ratigan, the main problem is that people aren't making enough noise. Capehart says that the people not only have to "burn up the phone lines to Congress", but also to hit the streets and protest in D.C.
Even though most politicians are totally corrupt, if many millions of Americans poured into the streets of D.C., a critical mass would be reached, and the politicians would start changing things in a hurry.
As PhD ecnonomist Dean Baker points out:
Baker is right about Vietnam.The elites hate to acknowledge it, but when large numbers of ordinary people are moved to action, it changes the narrow political world where the elites call the shots. Inside accounts reveal the extent to which Johnson and Nixon’s conduct of the Vietnam War was constrained by the huge anti-war movement. It was the civil rights movement, not compelling arguments, that convinced members of Congress to end legal racial discrimination. More recently, the townhall meetings, dominated by people opposed to health care reform, have been a serious roadblock for those pushing reform….
A big turnout ... can make a real difference.
Specifically - according to Daniel Ellsberg and many others - Richard Nixon actually planned on dropping a nuclear bomb on Vietnam Nixon also said he didn't care what the American people thought. He said that -- no matter what the public did or said -- he was going to escalate the war in Vietnam.
However, a well-known biographer says that Nixon backed off when hundreds of thousands of people turned out in Washington, D.C. to protest an escalation of the war.
Similarly, no matter how completely sold-out to the Wall Street giants D.C. politicians are, they would start paying attention to their real employers - the American people - if we make enough noise.
If 3 million Americans all peacefully surrounded the White House and Capitol Hill, holding signs saying "We're Not Leaving Until the Too Big to Fails which Caused the Economic Crisis are Reined In", things would change pretty fast.
3 million might sound like a lot of people. But many millions of people read popular alternative financial and economic news sites. You are probably one of millions of people who will read this essay (by the time it is published by some of the larger sites).
In other words, it's not even a question of convincing other people to go. We - those who read alternative financial websites - could do it ourselves.
If millions of us don't go protest in D.C., it's because we are choosing not to sacrifice a tiny bit in order to change things.
The bad guys are only winning because we - the American people - aren't making enough noise.
Not Now . . .
It is human nature to try to put things off until tomorrow. Tomorrow, when things are easier, we'll do it...
It is easy to despair that it is already too late. Should we whine and give up hope?
Well, about a month before the American Revolutionary War, Patrick Henry said:
They tell us, sir, that we are weak; unable to cope with so formidable an adversary. But when shall we be stronger? Will it be the next week, or the next year?If not now, when? Like Patrick Henry asked, when will we be stronger? When will the robber barons be weaker?
If we're going to save America through non-violent protests, now is the time.
To hell with circumstances; I create opportunities.
- Bruce Lee
There is no act too small, no act too bold. The history of social change is the history of millions of actions, small and large, coming together at points in history and creating a power that governments cannot suppress.
- Howard Zinn, historian
The power of an aroused public is unbeatable.
- Dr. Helen Caldicott
The most powerful weapon on earth is the human soul on fire.
-Ferdinand Foch
In times of danger large groups rise to the highest pitch of enthusiasm, courage and sacrifice . . . Mankind will be refashioned and history rewritten when this law is understood and obeyed.
-Helen Keller
Never doubt that a small group of thoughtful, committed citizens can change the world. Indeed, it's the only thing that ever has.
- Margaret Mead
We must remember that one determined person can make a significant difference, and that a small group of determined people can change the course of history.
-Sonia Johnson
You let one ant stand up to us - then they all might stand up. Those puny little ants outnumber us a 100 to one. And if they ever figure that out, there goes our way of life.
- Hopper (a grasshopper who is the leader of the gang of thugs who are stealing money from the other bugs, speaking to fellow grasshoppers in the Disney/Pixar movie A Bug's Life)
If you don't like the news, go out and make some news of your own.
- Scoop Nisker
Sunday, November 15, 2009
"War ALWAYS Causes Recession"
PhD economist Marc Faber predicts that the U.S. will launch a war to distract people from the bad economy.
China's largest media outlet - Sohu.com - wrote in October 2008 that the Rand corporation, a leading U.S. military advisor, lobbied the Pentagon for a war to be started with a major foreign power in an attempt to stimulate the American economy:
According to French media, well-known U.S. think tank RAND Corporation ... has submitted [to the Pentagon] an evaluation report assessing the wage a war to shift the feasibility of the current economic crisis...
(Google's translation services are crude approximations, but Yihan Dai confirmed the translation of the original).
Continued deepening of the U.S. sub-prime mortgage crisis and economic downturn, developed to a certain extent, is likely to trigger a war in order to achieve the purpose of the crisis passed.
Is Faber right? Is the Sohu.com report accurate?
I don't know. For example, I won't take the Sohu.com claim very seriously until someone can point to the French media source, so that I can assess it's credibility.
However, "military Keynesianism" - using military spending to stimulate the economy - has been U.S. policy for half a century. And the economist who coined that term said that such a policy always and "inexorably" leads to "an actual war" in order to justify all of the military spending.
Therefore, any studies which disprove the efficacy of war as an economic stimulus -see this and this - are important for balance.
To try to sort some of this out, I spoke with a PhD professor of economics with a background in international conflict in July 2008 to find out whether war is really good for the economy.
I asked if conventional wisdom that war is good for the economy is true, especially given that all of the spending on the war in Iraq seems to have weakened America's economy (or at least, greatly increased its debt).
The economist explained the seeming paradox:
"War always causes recession. Well, if it is a very short war, then it may stimulate the economy in the short-run. But if there is not a quick victory and it drags on, then wars always put the nation waging war into a recession and hurt its economy."Given that America has been fighting both the Afghanistan and Iraq wars longer than it fought WWII, the exception obviously doesn't apply.
Can America go beat up some poorly-armed country to get a quick war?
It is more unlikely than many assume. Given that many believe that the U.S. started the Iraq war based on false pretenses, and that the Iraq war was really about oil (see this, this, this, this and this), I am skeptical that many would buy America's stated justifications for another war.
Indeed, the Sohu.com article – even if wholly untrue – proves my point.
In addition, even a war against a small, poorly-armed and resource-poor country could be considered a proxy war. In other words, other heavily-armed countries might fight the U.S. through local proxies, dragging the war out for years, just as the U.S. did with Russia in Afghanistan. America today is not the empire it was even 10 years ago, and - as Afghanistan and Iraq show - America no longer has the financial resources to project force and impose its will world-wide.
The bottom line is that anyone advocating for war to help our economy is mistaken.
Saturday, November 14, 2009
Former Vice President of Dallas Fed: Tarp Didn’t Restore Health of Banking System
Newsweek has a one year retrospective on the Tarp bailouts which contains the following important quotes:
"It hasn't done what [Paulson] said it would," says Jerry O'Driscoll, a former vice president of the Dallas Federal Reserve and a senior fellow at the Cato Institute. "Yes, it saved some banks from going under, but did it restore the health of the banking system? Absolutely not."
***
"They didn't extract sensible terms," says Simon Johnson, former chief economist at the IMF. Johnson points out that Paulson didn't ask of its own banks what the U.S. regularly asks of developing countries when cleaning up their banking systems. "One of the first things that's done is to fire the managers that oversaw the problems," says Johnson. "Yet shockingly, this hasn't happened in the U.S. These guys are still there for the most part."
Hayek: “Emergencies Have Always Been the Pretext on Which the Safeguards of Individual Liberty Have Eroded”
Well-known Austrian economist Friedrich von Hayek wrote:
"Emergencies” have always been the pretext on which the safeguards of individual liberty have eroded.
Rahm Emanuel famously said:
Never let a serious crisis go to waste. What I mean by that is it's an opportunity to do things you couldn't do before.
Naomi Klein documented in the Shock Doctrine that the Neoliberals and Chicago school followers advocated a kind of "disaster capitalism". Specifically, whenever a natural, economic, war-related, or other disaster strikes, these folks pounce and use the opportunity to quickly impose a brand of economic policy which benefits the elite at the cost of everyone else (by increasing unemployment, pushing the cost of essential goods through the roof, and otherwise increasing poverty), while people are still in shock and before they can react.
Publishers Weekly's review of the Shock Doctrine puts it this way:
The neo-liberal economic policies—privatization, free trade, slashed social spending—that the Chicago School and the economist Milton Friedman have foisted on the world are catastrophic in two senses, argues this vigorous polemic. Because their results are disastrous—depressions, mass poverty, private corporations looting public wealth, by the author's accounting—their means must be cataclysmic, dependent on political upheavals and natural disasters as coercive pretexts for free-market reforms the public would normally reject.
Amazon's review of Klein's book states:
"At the most chaotic juncture in Iraq'' civil war, a new law is unveiled that will allow Shell and BP to claim the country's vast oil reserves… Immediately following September 11, the Bush Administration quietly outsources the running of the 'War on Terror' to Halliburton and Blackwater… After a tsunami wipes out the coasts of Southeast Asia, the pristine beaches are auctioned off to tourist resorts… New Orleans residents, scattered from Hurricane Katrina, discover that their public housing, hospitals and schools will never be re-opened." Klein not only kicks butt, she names names, notably economist Milton Friedman and his radical Chicago School of the 1950s and 60s which she notes "produced many of the leading neo-conservative and neo-liberal thinkers whose influence is still profound in Washington today."And Pulitzer prize winning journalist David Cay Johnston provided an interesting example of disaster capitalism, noting that 2 days after 9/11, Congress was thinking about how to help the ultra-wealthy:
I am not passing judgment on whether estate taxes are good or bad. I am simply saying that emergencies and disasters are always used by the powerful to make the changes they want - even if wholly unrelated to the emergency.[Johnston]: Both parties are doing this. They’re doing it because they’re listening to a narrow group of very well to do people who do not want to pay taxes, who do not want to share in the expenses of the country that has made them rich. And they want you to pay their taxes. Those are the people who get access. Every politician will say you to, you can’t buy my vote. Generally, that’s true. The problem is that you and I don’t have the real access, and the proof that Congress is thinking about the super rich came two days after 9/11. The House Republican leadership introduced ten bills to address 9/11. One of them was a tax bill. What did it do? It gave estate tax relief, which did nothing for the firefighters and police officers and army sergeants at their desk and nurses and the busboy at the World Trade Center. All of those people that were killed. A tiny handful of people, but that’s what Congress thought these people needed, was estate tax relief even though 99% wouldn’t pay estate taxes.
[Interviewer:] It’s slipping it in as a very opportune time.
[Johnston]: That was just for this group of people. That was just for this group of people, but it’s indicative of what Congress is thinking about, what’s on the minds of Congress are not the concerns of ordinary Americans who want to educate their children, you know, who want to engage in enjoying life. Their concerns are about the super rich and within the super rich, those who are very anti-tax.
Would Our Government Really Start a War to Try to Stimulate the Economy?
I've written two essays attempting to disprove "military Keynesianism" - the idea that military spending is the best stimulus. See this and this.
In response, a reader challenged me to prove that anyone would advocate military spending or war as a fiscal stimulus.
In fact, the concept of military Keynesianism is so widespread that there are some half million web pages discussing the topic.
And many leading economists and political pundits sing its praises.
For example, Martin Feldstein - chairman of the Council of Economic Advisers under President Reagan, an economics professor at Harvard, and a member of The Wall Street Journal's board of contributors - wrote an op-ed in the Journal last December entitled "Defense Spending Would Be Great Stimulus".
And as the Cato Institute notes:
Bill Kristol agrees. Noting that the military was "spending all kinds of money already," Mr. Kristol wondered aloud, "If you're buying 2,000 Humvees a month, why not buy 3,000? If you're refurbishing two military bases, why not refurbish five?"Professors of political economy Jonathan Nitzan and Shimshon Bichler write:
***This is not the first time that defense spending has been endorsed as a way to jump-start the economy. Nearly five decades ago, economic advisers to President Kennedy urged him to increase military spending as an economic stimulus...
Similar arguments are heard today. The members of Connecticut's congressional delegation have been particularly outspoken in their support for the Virginia-class submarine, and they haven't been shy about pointing to the jobs that the program provides in their home state. The Marine Corps' V-22 Osprey program wins support on similar grounds. Despite serious concerns about crew safety and comfort, the V-22 program employs workers in Pennsylvania, New Jersey, Delaware and Texas, and a number of other states.
Theories of Military Keynesianism and the Military-Industrial Complex became popular after the Second World War, and perhaps for a good reason. The prospect of military demobilization, particularly in the United States, seemed alarming. The U.S. elite remembered vividly how soaring military spending had pulled the world out of the Great Depression, and it feared that falling military budgets would reverse this process. If that were to happen, the expectation was that business would tumble,unemployment would soar, and the legitimacy of free-market capitalism would again be called into question.Are they right about NSC-68?
Seeking to avert this prospect, in 1950 the U.S. National Security Council drafted a top-secret document, NSC-68. The document, which was declassified only in 1977, explicitly called on the government to use higher military spending as a way of preventing such an outcome.
Well, PhD economist Robert Higgs confirms the importance of NSC-68:
Previously administration officials had encountered stiff resistance from Congress to their pleas for a substantial buildup along the lines laid out in NSC-68, a landmark document of April 1950. The authors of this internal government report took a Manichaean view of America’s rivalry with the Soviet Union, espoused a permanent role for the United States as world policeman, and envisioned U.S. military expenditures amounting to perhaps 20 percent of GNP. But congressional acceptance of the recommended measures seemed highly unlikely in the absence of a crisis. In 1950 “the fear that [the North Korean] invasion was just the first step in a broad offensive by the Soviets proved highly useful when it came to persuading Congress to increase the defense budget.” As Secretary of State Dean Acheson said afterwards, “Korea saved us.” The buildup reached its peak in 1953, when the stalemated belligerents in Korea agreed to a truce.And Chalmers Johnson - Professor emeritus of the University of California, San Diego, and former CIA consultant - writes:
This is military Keynesianism — the determination to maintain a permanent war economy and to treat military output as an ordinary economic product, even though it makes no contribution to either production or consumption.You can read NSC-68 here.This ideology goes back to the first years of the cold war. During the late 1940s, the US was haunted by economic anxieties. The great depression of the 1930s had been overcome only by the war production boom of the second world war. With peace and demobilisation, there was a pervasive fear that the depression would return. During 1949, alarmed by the Soviet Union’s detonation of an atomic bomb, the looming Communist victory in the Chinese civil war, a domestic recession, and the lowering of the Iron Curtain around the USSR’s European satellites, the US sought to draft basic strategy for the emerging cold war. The result was the militaristic National Security Council Report 68 (NSC-68) drafted under the supervision of Paul Nitze, then head of the Policy Planning Staff in the State Department. Dated 14 April 1950 and signed by President Harry S Truman on 30 September 1950, it laid out the basic public economic policies that the US pursues to the present day.
In its conclusions, NSC-68 asserted: “One of the most significant lessons of our World War II experience was that the American economy, when it operates at a level approaching full efficiency, can provide enormous resources for purposes other than civilian consumption while simultaneously providing a high standard of living”.
With this understanding, US strategists began to build up a massive munitions industry, both to counter the military might of the Soviet Union (which they consistently overstated) and also to maintain full employment, as well as ward off a possible return of the depression. The result was that, under Pentagon leadership, entire new industries were created to manufacture large aircraft, nuclear-powered submarines, nuclear warheads, intercontinental ballistic missiles, and surveillance and communications satellites. This led to what President Eisenhower warned against in his farewell address of 6 February 1961: “The conjunction of an immense military establishment and a large arms industry is new in the American experience” — the military-industrial complex.
By 1990 the value of the weapons, equipment and factories devoted to the Department of Defense was 83% of the value of all plants and equipment in US manufacturing. From 1947 to 1990, the combined US military budgets amounted to $8.7 trillion. Even though the Soviet Union no longer exists, US reliance on military Keynesianism has, if anything, ratcheted up, thanks to the massive vested interests that have become entrenched around the military establishment.
Leading political journalist John T. Flynn wrote in 1944 :
Militarism is the one great glamorous public-works project upon which a variety of elements in the community can be brought into agreement.But Flynn warned that:
Inevitably, having surrendered to militarism as an economic device, we will do what other countries have done: we will keep alive the fears of our people of the aggressive ambitions of other countries and we will ourselves embark upon imperialistic enterprises of our own.Indeed, the creator of the theory of military Keynesianism himself warned that those who followed such thinking would fearmonger, appeal to patriotism and get us into wars in order to promote this kind of economic "stimulus". As The Independent wrote in 2004:
I disagree that this is a partisan issue. The Independent piece portrays the "neo-liberal right" as special warmongers; I don't believe there is much difference with the "neo-liberal left", or "neo-conservative right", or whatever. Indeed, political labels are fairly meaningless. What is important is the actions one takes, not his rhetoric about his actions.Military-fuelled growth, or military Keynesianism as it is now known in academic circles, was first theorised by the Polish economist Michal Kalecki in 1943. Kalecki argued that capitalists and their political champions tended to bridle against classic Keynesianism; achieving full employment through public spending made them nervous because it risked over-empowering the working class and the unions.
The military was a much more desirable investment from their point of view, although justifying such a diversion of public funds required a certain degree of political repression, best achieved through appeals to patriotism and fear-mongering about an enemy threat - and, inexorably, an actual war.
At the time, Kalecki's best example of military Keynesianism was Nazi Germany. But the concept does not just operate under fascist dictatorships. Indeed, it has been taken up with enthusiasm by the neo-liberal right wing in the United States.
New Derivatives Legislation "Was Probably Written by JPMorgan and Goldman Sachs"
As I have repeatedly written (see this and this), the new derivatives legislation is so bad that it probably increases - rather than decreases - the risk to the financial system.
William Greider has a great piece in The Nation pointing out:
For background, see this and this.Who drafted this dubious piece of legislation? Bankers (or their lawyers) did. The leading sellers of derivatives are an exclusive club of five very large financial institutions--Citigroup, JPMorgan Chase, Bank of America, Morgan Stanley and Goldman Sachs--that hold 95 percent of the derivatives exposure among the largest banks (the total contract value exceeds $290 trillion). These are the same folks who toppled the global economy and compelled government to intervene with gigantic bailouts.
Michael Greenberger, a University of Maryland law professor and veteran federal regulator, studied the House committee's 187-page bill and detected the fine needlework of Wall Street lawyers. "It had to be written by someone inside the banks," Greenberger said, "because buried every few pages is a tricky and devilish 'exception.' It would greatly surprise me if these poison pills originated from anyone on Capitol Hill or the Treasury."
A well-informed Congressional source confirmed that the original language in the draft legislation was written by financial-industry experts. It "was probably written by JPMorgan and Goldman Sachs," he told me, "and possibly the Chicago Mercantile Exchange." The Chicago exchange trades commodity futures--hog bellies, beef, grains--and more exotic derivatives. It is a rival to Wall Street but very close to agribusiness interests like Cargill, the giant grain trader, that make heavy use of derivatives.
Washington insiders may not be shocked to learn that private-interest groups provided the draft bill. This is what lobbyists often do for the legislative process, especially on complex subjects like taxation and regulatory law. But the legislation was delivered to the House Financial Services Committee by Blue Dog Democrats, not lobbyists. There are fifteen Blue Dogs and like-minded members on the committee. Together they make up more than one-third of the committee's Democratic majority (forty-two Democrats, twenty-nine Republicans).
"The conduit for the draft text was Blue Dogs and conservative Democrats," my source explained...
The Blue Dogs claimed they were speaking for business, not bankers, but this too involved a little sleight of hand by industry lobbyists. Last summer, an official of the Securities Industry and Financial Markets Association told colleagues at a private industry meeting that since the bankers have damaged credibility in Washington, they should send their customers to push the bankers' position on Capitol Hill. Sure enough, representatives from various industrial and agricultural sectors showed up to testify as expert witnesses and demand exemption from regulation as the "end users" of derivatives. Bankers told their clients that regulation would raise their costs. Never mind the costs to the country if derivatives blow up again...
The House Financial Services Committee is a prized assignment and known informally among members as a "money committee," not because it deals with money issues but because its members have an easier time raising campaign funds from the banks and financial firms under their jurisdiction...
Money also explains why the committee is top-heavy with Blue Dogs. House Speaker Nancy Pelosi put them there, along with other freshmen and sophomores, knowing it can help them win re-election. She was encouraged by Representative Rahm Emanuel...
As recent election returns suggest, if the president continues to soft-sell reform, he is at risk of being identified with the old order in Wall Street. The longer Congress tries to placate the bankers with meek reforms, the sooner Democrats will discover this is really dumb politics.
Friday, November 13, 2009
South Korean Economy Grew at an 11% Annual Rate in Q2
Former international merchant banker and Money Morning contributing author Martin Hutchinson notes that South Korea:
- Grew at an annual rate of 11% in the second quarter
- Will report a second-consecutive double-digit advance when it reports on Monday
- Korea’s current account balance once again shows a healthy surplus, and Fitch's said that a downgrade would be unnecessary, and that Korea could expect to run a budget surplus in 2011
- The Korea Composite Stock Price Index (KOSPI) is up 65% from its low point in December 2008
- Exports have recovered, largely due to surging demand from China
- "Korea’s government spending as a percentage of GDP is one of the lowest of the world’s most-affluent developed economies. That means it will be much less of a burden than on the Korean economy than will similar outlays in the higher-spending Japan, United States and European Union."
Mexico Becomes World's Cheapest Country for Manufacturing U.S. Goods
AlixPartners provides an interesting fact concerning Mexico.
As Keith Fitz-Gerald - chief investment strategist for Money Morning and The Money Map Report - notes:
There are a number of additional reasons why Keith Fitz-Gerald likes Mexico as an investment.According to corporate consultant AlixParnters, Mexico has leapfrogged China to be ranked as the cheapest country in the world for companies looking to manufacture products for the U.S. market. India is now No. 2, followed by China and then Brazil.
In fact, Mexico’s [has such big] cost advantages and has become so cheap that even Chinese companies are moving there to capitalize on the trade advantages that come from geographic proximity.
The Weak Dollar and the Too Big to Fails
Former chief IMF economist Simon Johnson points out that the U.S. is intentionally weakening the dollar in order to bail out the too big to fails:
To bail out our banks, we need cheap money, and this implies some inflation. To finance our current account deficit, investors need to think they are buying inexpensive assets from us. Everything points to a cheaper dollar...
Short-term rates (controlled by the Fed) will stay low, while long-term rates (market-determined and affected by trust in our Treasury and Fed to keep the value of dollar strong) will rise as people fear their dollar investments will be debased. There is no doubt that both the Fed and the Bank of England know what is happening. The spread between short- and long-term rates (known as the “yield curve”) will rise, and banks will benefit; would-be home buyers and people with overdrafts or outstanding credit card balances pay more, while savers get little.This is how the public pays for the past losses of our financial system.
We don’t have to do this again and again. We could start by changing our financial system from the roots. We need to credibly remove the promise to bail out our large banks each time they fail. This means forcing them to hold more capital, dividing them up so they are smaller, and then letting them fail when they make poor gambles.
The Treasury’s past and current close connections to Goldman Sachs, Citigroup and other major investment banks illustrate how our own doom machine functions. We need to break up these “banks” so they are small enough to fail, and also ensure that no bank, regardless of its connections, is able to demand that the Fed and the Treasury support its solvency in the future to prevent financial collapse.
Senator Dorgan: "We Essentially Have Had Modern-Day Bank Robbers ... and There's Been No Accountability ... There's No Question the System Is Rigged"
Senator Byron Dorgan has some harsh words for the too big to fails:
It's one of the most frustrating things. We essentially have had modern-day bank robbers -- except that they wore gray suits and not masks -- and there's been no accountability for it ...
Every day we see energy speculators, war profiteers, managed health-care providers, media propagandists, and/or financiers given some unfair advantage over the average consumers and taxpayers, and the cumulative effect of the American people watching selfishness prevail over the public interest has been an undermining of the public's trust in government.
This "anything goes" approach to capitalism has injured the very economy we have aspired to create.I'm a big fan of the free-market system...This is not about a liberal or conservative philosophy. It is about making sure our economy and the free-market system work for everybody...
There's no question the system is rigged against the little guy. The bigger interests have a lot more information. They jerry-rig the system so that they always win.
Dorgan said 3 things are needed to fix the financial system:
One is to separate investment banks and FDIC-insured banks. Second, prohibit FDIC-insured banks from dealing in risky financial instruments on their own proprietary accounts... And third, abolish "too big to fail." If you're too big to fail, you're too big. Too big to fail is what I call no-fault capitalism.
Senator Dorgan was one of eight senators who stood up to oppose the repeal of the Glass-Steagall act in 1999, and said at the time:
I think we will in 10 years' time look back and say we should not have done this.
Thursday, November 12, 2009
Confirmed: Defense Spending Creates Fewer Jobs Than Other Types of Spending
Yesterday, I pointed out that a study by one of the leading economic modeling companies shows that military spending increases unemployment and decreases economic growth.
I have located a paper by economist Robert Pollin published in 2007 by The Political Economy Research Institute at the University of Massachusetts, Amherst - entitled "The U.S. Employment Effects of Military and Domestic Spending Priorities" - which concludes:
We present in Table 1 our estimate of the relative effects of spending $1 billion on alternative uses, including military spending, health care, education, mass transit, and construction for home weatherization and infrastructure repair."Military Keynesianism" - the idea that war is the best economic stimulus - is false.
[Click image for larger version]
The table first shows in column 1 the data on the total number of jobs created by $1 billion in spending for alternative end uses. As we see, defense spending creates 8,555 total jobs with $1 billion in spending. This is the fewest number of jobs of any of the alternative uses that we present. Thus, personal consumption generates 10,779 jobs, 26.2 percent more than defense, health care generates 12,883 jobs, education generates 17,687, mass transit is at 19,795, and construction for weatherization/infrastructure is 12,804. From this list we see that with two of the categories, education and mass transit, the total number of jobs created with $1 billion in spending is more than twice as many as with defense.


Update: Pollin published an updated version of his paper on October 20, 2009. The abstract summarizes their updated findings:
The authors compare the effects of a $1 billion military investment military and the same investment in clean energy, health care, education, or individual tax cuts. They show that non-military investments create a much larger number of jobs across all pay ranges. With a large share of the federal budget at stake, Pollin and Garrett-Peltier make a strong case that non-military spending priorities can create significantly greater opportunities for decent employment throughout the U.S. economy than spending the same amount of funds with the military.And here are a chart and table from the updated study:


Barrick Confirms that We Have Peak Gold
As I pointed out in September, there are strong arguments that we have "peak gold" - in other words, that the relatively easy-to-reach gold supplies are gone, and so supplies are getting more and more expensive to locate and extract.
Now, the world's biggest gold producer - Barrick - is saying the same thing:
Aaron Regent, president of the Canadian gold giant [Barrick], said that global output has been falling by roughly 1m ounces a year since the start of the decade. Total mine supply has dropped by 10pc as ore quality erodes, implying that the roaring bull market of the last eight years may have further to run.
"There is a strong case to be made that we are already at 'peak gold'," he told The Daily Telegraph at the RBC's annual gold conference in London.
"Production peaked around 2000 and it has been in decline ever since, and we forecast that decline to continue. It is increasingly difficult to find ore," he said.
For a thorough big picture analysis on gold, see this.
Wednesday, November 11, 2009
S&P's Chief Economist Confirms the Importance of Age Demographics
As I have previously noted, Japan's population is rapidly aging, and the U.S. age pyramid - while not as bad - is not nearly as young as that of Brazil or India's:
The chief economist for Standard and Poor's is now confirming the importance of national demographics:Which countries have the best demographics?
Let's start by looking at the "age pyramid" for the United States. The following 2 charts from the National Institutes of Health shows that the population is aging:
This graphic (courtesy of Ed Stephan) shows the U.S. age pyramid from from 1950 through 2050:
male female 
Population of the United States, by Age and Sex,
1950-2050 (millions)
information source: International Data Base, U.S. Census Bureau;
supplied pyramids were modified using Canvas, GraphicConverter and GIFBuilder.As NIH notes:
The first of the postwar baby boom cohort, born 1946–1964, will turn 55 years in 2001. In just three decades, an extraordinary change in the age structure of the United States is anticipated. By 2030, one in five persons (20% of the U.S. population) will be aged 65 or older, increasing from the present ratio of one in nine persons (12.8%). The number of persons in the 65 and older age group will more than double, increasing from the current 34 million persons to 70 million persons. Moreover, within the older segment of the population, because of longer life expectancy and additional persons reaching older ages, there will be age shifts resulting in the 85 and older population more than doubling in size from 4.3 million persons to approximately 8.9 million persons.An aging U.S. population means less productive workers, less big-spending consumers, and more dependent elders...
Brazil has a much younger age demographic.
And India's is even younger than Brazil's.
The following chart shows that Japan has the worst demographics of all, with a staggering percentage of elderly who need to be taken care of by the young:
Chart 2: Old Age Dependency Ratios for Selected Countries
Source: http://data.un.org/


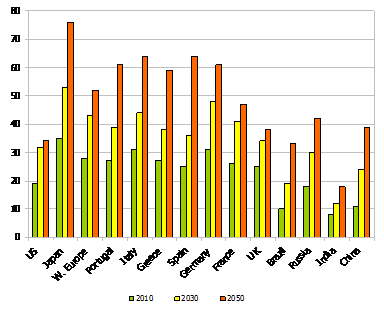
In other words, America's age demographics aren't as bad as Japan's, but they aren't helping, either.But I don't think [a lost decade in the U.S. is] as likely over here. For one thing, one of the problems in Japan was the demographics. And we don't have the problem of a declining population to deal with, although the labor force is going to slow down considerably as soon as the baby boomers retire.
Military Spending is INCREASING Unemployment and REDUCING Economic Growth
I have written extensively on the fact that this is not a normal cyclical recession, and we're not in the type of "jobless recovery" which we've had a couple of times in the last 50 years. Unemployment will continue rising in America for some time, which will make a real, sustainable recovery very difficult.
The heads of two Federal Reserve banks are now saying something similar:
But instead of doing anything to encourage a sustainable recovery in employment - such as rebuilding America's manufacturing base, or breaking up the too big to fails so that the smaller banks have a chance to grow and lend more to individuals and small businesses (see this and this) - the government has simply thrown money at the banks.Janet Yellen, president of the Federal Reserve Bank of San Francisco, and Dennis Lockhart, president of the Federal Reserve Bank of Atlanta, warned that rising unemployment could crimp consumers, restraining the recovery. Consumer spending accounts for about 70 percent of economic activity.
Moreover - contrary to what you might have heard - PhD economist Dean Baker pointed out yesterday that America's massive military spending on unnecessary and unpopular wars actually lowers economic growth and increases unemployment:
Defense spending means that the government is pulling away resources from the uses determined by the market and instead using them to buy weapons and supplies and to pay for soldiers and other military personnel. In standard economic models, defense spending is a direct drain on the economy, reducing efficiency, slowing growth and costing jobs.
A few years ago, the Center for Economic and Policy Research commissioned Global Insight, one of the leading economic modeling firms, to project the impact of a sustained increase in defense spending equal to 1.0 percentage point of GDP. This was roughly equal to the cost of the Iraq War.Note 1: Global Insight is:
Global Insight’s model projected that after 20 years the economy would be about 0.6 percentage points smaller as a result of the additional defense spending. Slower growth would imply a loss of almost 700,000 jobs compared to a situation in which defense spending had not been increased. Construction and manufacturing were especially big job losers in the projections, losing 210,000 and 90,000 jobs, respectively.
The scenario we asked Global Insight to model turned out to have vastly underestimated the increase in defense spending associated with current policy. In the most recent quarter, defense spending was equal to 5.6 percent of GDP. By comparison, before the September 11th attacks, the Congressional Budget Office projected that defense spending in 2009 would be equal to just 2.4 percent of GDP. Our post-September 11th build-up was equal to 3.2 percentage points of GDP compared to the pre-attack baseline. This means that the Global Insight projections of job loss are far too low...
The projected job loss from this increase in defense spending would be close to 2 million. In other words, the standard economic models that project job loss from efforts to stem global warming also project that the increase in defense spending since 2000 will cost the economy close to 2 million jobs in the long run.
Recognized as the most consistently accurate forecasting company in the world.Note 2: A paper published in 2007 by the The Political Economy Research Institute at the University of Massachusetts, Amherst entitled "The U.S. Employment Effects of Military and Domestic Spending Priorities" concludes:
We present in Table 1 our estimate of the relative effects of spending $1 billion on alternative uses, including military spending, health care, education, mass transit, and construction for home weatherization and infrastructure repair...Note 3: I honor the brave veterans and active-duty soldiers who have served our country. They are not responsible for the policies of the civilian leadership. Indeed, if you talk to soldiers, many will tell you they think we are involved in wars we shouldn't be in.
As we see, defense spending creates 8,555 total jobs with $1 billion in spending. This is the fewest number of jobs of any of the alternative uses that we present. Thus, personal consumption generates 10,779 jobs, 26.2 percent more than defense, health care generates 12,883 jobs, education generates 17,687, mass transit is at 19,795, and construction for weatherization/infrastructure is 12,804. From this list we see that with two of the categories, education and mass transit, the total number of jobs created with $1 billion in spending is more than twice as many as with defense.
Note 4: I am for a strong defense. That's not what this is about.
But we got into the Iraq war based on the false linkage of Saddam and 9/11, and false claims that Saddam had WMDs. Nobel prize winning economist Joseph Stiglitz says that the Iraq war will cost $3-5 trillion dollars.
And experts say that the Iraq war has increased the threat of terrorism. See this, this, this, this, this and this.
(Incidentally, torture also reduces our national security).
Financial Reform Doesn't Need to be Complicated
In response to Senator Dodd's proposed bill - which uses a lot of buzzwords that sound like reform, but really just maintains the status quo - several writers have forcefully argued that we need to focus on the actual purpose of banking.
As a number of people have pointed out, any bill which is 1,136 pages long will contain loopholes big enough to drive a truck through and more holes than swiss cheese. Almost no one will actually read the bloody thing, those that do will see that it is rife with ambiguities. And it will get so marked up by the time that it works its way through various committees that - by the time it is passed - there will be more hole than swiss cheese.
Unless financial legislation addresses the big picture - why do we have banks and what do we want them to do - nothing will really change.
One blogger sums up the big picture argument pretty succinctly:
I have repeatedly written that Glass-Steagall should be reenacted, and that banks should choose either to act as traditional, safe depository institutions or as speculative funds, but not both. I have also argued that companies which extend credit should be treated like public utilities. But the above-quoted blogger hits the nail on the head with very few words: we need to focus on the overall purpose of the banks and the financial systems.I worry though that — despite the healthy impetus and rhetoric [in the Dodd bill] — that the center of thought on all this seems stuck in the same equations, theories, ideas and general zeitgeists about efficiency and all that. Just a bit of big-time tweaking is all we need... But a new coat of paint on a rotting wall will eventually chip and crack.
No, we need to make them really think. Let’s have a “Preamble” to this legislation, like the Bill of Rights is to the Constitution, that sets up the Philosophical ground. What’s a bank for? What’s a financial system for? What is the public good?
And fund manager Marshall Auerback provides a detailed proposal for a public purpose test:
We feel that the ‘race to the regulatory bottom’ could easily be solved via a simple mechanism: If you don’t fall in line with our regulatory requirements, you’re simply denied a banking license to operate in this country. Problem solved. The United States is the biggest banking market in the world. Do you think any major bank would willingly vacate this market?And even if the “too big to fail” behemoths decided to transplant a bunch of their operations elsewhere, the country would still be left with thousands of community banks which could fill the void and better fulfill the public purpose described by Mr Blankfein: namely, to “help companies to grow by helping them to raise capital”, rather than extracting their pound of flesh via grotesquely high financial intermediary fees, as is the case today...
WHO controls the banks is ultimately less important than HOW we control the banks’ activities. Oversight is all very nice, but at times it pays to get back to first principles. What on earth is the public purpose of these things?
Banks are set up and supported by government for the further benefit of the macro economy via providing a payments system and lending in a way that is specifically defined by regulators. Newsflash: the public purpose of banking is NOT to provide profits per se to shareholders. Rather, the provision of the ability to earn profits is only a tool used to support the attendant public purpose. Banks should only be allowed to lend directly to borrowers, and then service and keep those loans on their own balance sheets. There is no further public purpose served by selling loans or other financial assets to third parties, but there are substantial real costs to government in regulating and supervising those activities. There are severe consequences for failure to adequately regulate and supervise those secondary market activities as well.
Banks should be prohibited from engaging in any secondary market activity because it serves no public purpose and may result in severe social costs in the case of regulatory and supervisory lapses. Some argue that these areas might be profitable for the banks, but this is not a reason to extend government sponsored enterprises into those areas. Therefore, banks should not be allowed to buy (or sell) credit default insurance. The public purpose of banking as a public/private partnership is to allow the private sector to price risk, rather than have the public sector pricing risk through publicly owned banks.
If a bank instead relies on credit default insurance, then it is transferring that pricing of risk to a third party, which is counter to the public purpose of the current public/private banking system. Banks should not be allowed to engage in proprietary trading or any profit-making ventures beyond basic lending. If the public sector wants to venture out of banking for some presumed public purpose it can be done through other outlets.
If the activities of the banks are not facilitating the production and movement of real goods and services what public purpose do they serve? It is clear they have made a small number of people fabulously wealthy. It is also clear that they have damaged the prospects for disadvantaged workers in many parts of the world.
It’s more obvious to all of us now that when the system comes unstuck through the complexity of these transactions and the impossibility of correctly pricing risk, the real economies across the globe suffer. The consequences have been devastating in terms of lost employment and income and lost wealth.
All governments should sign an agreement which would make all financial transactions that cannot be shown to facilitate funding for real goods and services illegal. Simple as that. When we keep these principles at the front of the argument, we can see that what Senator Dodd and Congressman Frank are arguing about is akin to how to rearrange the deck chairs on the Titanic.
Perfect Inverse Correlation Between the Dollar and the Dow
Karl Denninger - who is always worth reading - shares 2 stunning charts which show the inverse correlation between the dollar and the Dow:
That is an overlaid chart (as close as I can easily get them to register) on the dollar and The S&P 500 from the March lows to today.
Notice the near-perfect inverse correlation. The Dollar goes up, the market goes down. The Dollar goes down, the market goes up.
Now today, literally minute-by-minute:


Same correlation - near-perfect.
Tuesday, November 10, 2009
Statistics: Wealth in America (and in Congress)
A report by University of California, Berkeley economics professor Emmanuel Saez concludes that income inequality in the United States is at an all-time high, surpassing even levels seen during the Great Depression.
The report shows that:
- Income inequality is worse than it has been since at least 1917
- "The top 1 percent incomes captured half of the overall economic growth over the period 1993-2007"
- "In the economic expansion of 2002-2007, the top 1 percent captured two thirds of income growth."
On the other hand, billionaires have never had it better (and see this).
Of the 535 members of Congress, over 44% - 237 to be exact - are millionaires. Fifty have net worths of at least $10 million, and seven are worth more than $100 million. By comparison, around 1% of Americans are millionaires. There is no other minority group that is as overrepresented in Congress. See this.
Senator Dodd's Bill: Trying to Prop Up a Broken System
I posted an 11-page summary of Senator Dodd's financial reform bill earlier today.
After receiving input from one of the top experts on credit rating agencies and various other smart people, I have now formed an opinion about Dodd's bill.
Specifically, Dodd's bill - while sounding good - is really an all-out attempt to save the current, broken system.
Dodd's bill contains a number of concepts and catch-phrases that sound like reform. But the bill would actually:
- Keep the current Federal Reserve system, even though it is a wholly-failed system (see this, this and this). True, the bill would take away some of the Fed's regulatory oversight powers, but the Fed has never used them anyway, so it is really maintaining the status quo
- Keep the current NRSRO credit rating system - maintaining Moody's, S&P and Fitch as a government-endorsed rating monopoly - even though that is a wholly-failed system
- While saying it "ends too big to fail", the bill would actually make sure that attempts to immediately break up the giant insolvent black holes dragging our economy down - such as Senator Sanders' bill - will be killed
We can go on and on, as the bill - while using a lot of nice language - attempts to prop up just about every aspect of the current system, while appointing ("trust us, we're different") regulators to oversee things. It does nothing to try to prevent future forms of looting (which Congressmen Grayson, Clay and Miller attempted to do in their bill).
But we cannot be sure that such regulators won't be subject to the same regulatory capture as all of the current regulators have suffered. Or that Senator Dodd has suffered, for that matter.
Only by taking away monopoly power from the too big to fails, and the NRSROs, and the Fed can we ever have a stable economy.
In addition, the economy cannot recovery until trust is restored in the financial system, and trust will not be restored unless the fraud behind the financial crash is prosecuted. Dodd's bill ignores past fraud.


 Posts



